

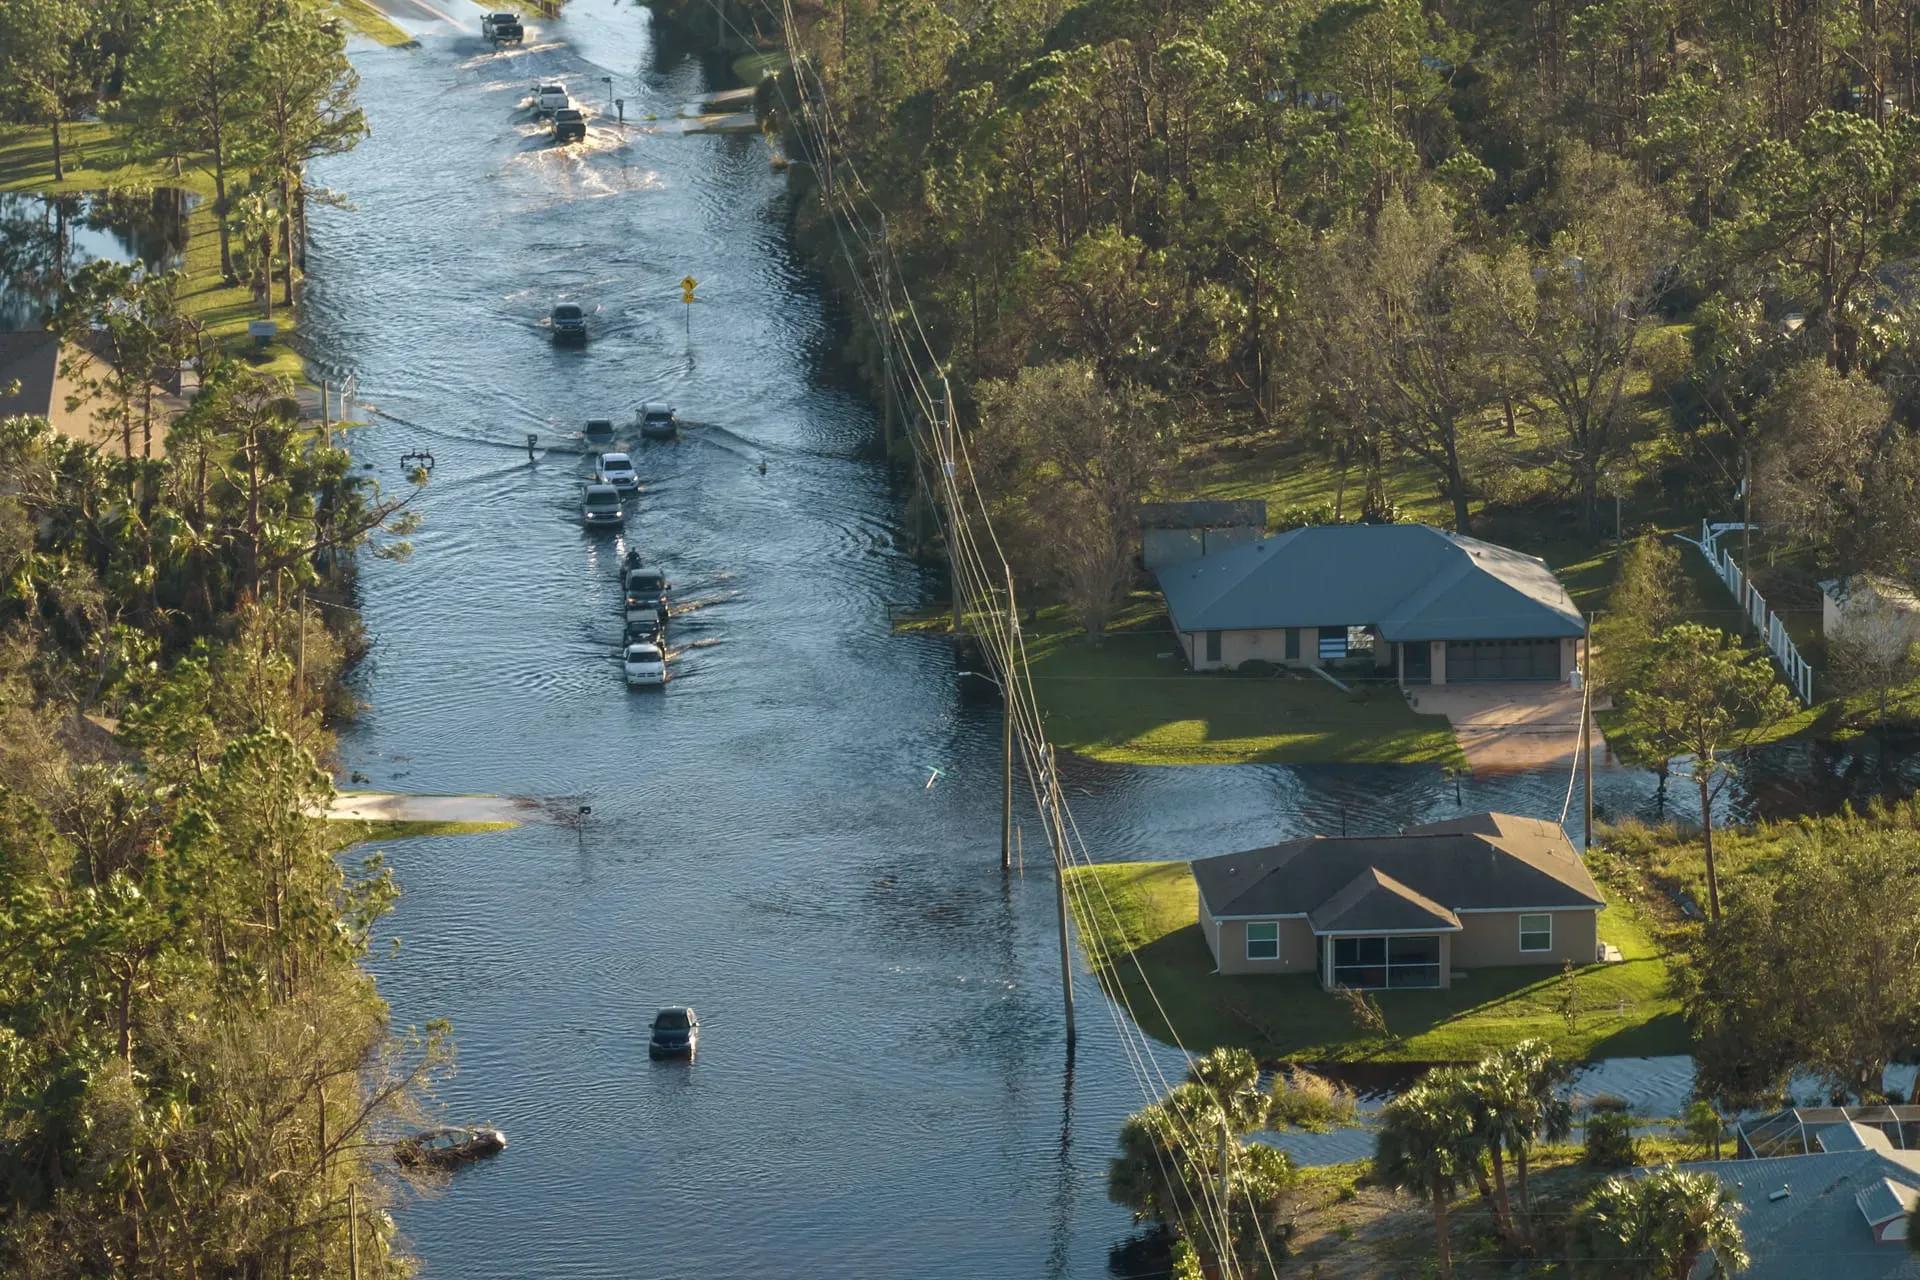
flooding in a community
Flood insurance confusion lingers because coverage details are rarely reviewed until risk feels immediate and emotions are already running high. A slightly different version of common flood insurance misunderstandings continues shaping choices as flooding events become more frequent across the country. Southern Ambit Insurance reminds policyholders that “the biggest losses usually come from assumptions, not from a lack of available coverage.” The discussion below explains why these misunderstandings keep resurfacing and how they quietly influence decisions long before water enters a home.
Why Flood Insurance Misunderstandings Keep Returning
Confusion surrounding flood insurance often grows from casual advice, outdated information, or rules that changed without much public attention. Many homeowners rely on stories shared after past storms and treat those stories as current guidance. Professional experience shows that even careful planners can be caught off guard when flood policies behave differently than expected, especially after seeing claims reduced or denied for reasons no one explained ahead of time.
• Flood insurance operates separately from homeowners coverage
• Federal flood rules evolve faster than public awareness
• Past storm experiences shape long-term beliefs
1. Flood Insurance Is Optional
A large number of property owners assume flood insurance is a personal preference rather than a condition tied to certain mortgage agreements. Federally backed lenders commonly require flood coverage for properties located in high-risk flood zones, as outlined by FEMA, yet this requirement is often overlooked until paperwork appears at closing. That misunderstanding lingers because enforcement happens quietly and far from everyday conversations. Assumptions settle in early.
• Federally backed loans may require flood coverage
• Flood zone designations influence lender rules
• Requirements exist long before storms arrive
2. Homeowners Insurance Covers Flooding
Standard homeowners insurance policies clearly exclude flood damage, a point emphasized by FEMA and the National Flood Insurance Program. Damage from rising water, storm surge, or overflowing waterways falls outside typical homeowners coverage even when the destruction looks similar to other water-related losses. This misunderstanding survives because everyday language blurs the meaning of flood versus water damage. Policy definitions carry weight.
• Flood damage originates from outside the structure
• Homeowners coverage focuses on internal water sources
• Terminology creates lasting confusion
3. Only High Risk Areas Flood
Flood maps often give homeowners in moderate or low-risk zones a false sense of safety. FEMA reports that about one quarter of flood insurance claims come from properties located outside officially designated high-risk areas. That figure surprises many people every year. The misunderstanding persists because maps feel fixed even though weather patterns and development continuously reshape flood behavior.
• Flood zones reflect likelihood, not guarantees
• Rainfall patterns shift over time
• New construction changes drainage flow
4. Flood Insurance Is Too Expensive
Cost assumptions surrounding flood insurance usually trace back to outdated premium stories shared after major disasters. FEMA data shows many flood policies are priced lower than expected, particularly for homes outside high-risk zones. This belief sticks around because pricing conversations rarely happen unless a renewal notice appears. Silence allows exaggerated numbers to spread.
• Premiums depend on elevation and structure type
• Lower-risk zones often carry reduced rates
• Old cost stories persist for years
5. Federal Aid Replaces Coverage
Disaster assistance is frequently mistaken for insurance, even though FEMA clearly states that most assistance arrives as loans rather than grants. Flood insurance pays based on policy terms regardless of disaster declarations, while federal aid depends on government approval and repayment obligations. This misunderstanding continues because news coverage often highlights relief payments without explaining long-term repayment. Context fades quickly.
• Federal aid requires an official disaster declaration
• Many assistance programs involve repayment
• Insurance responds according to policy language
6. Flood Insurance Pays Immediately
Most new flood insurance policies include a standard 30-day waiting period under NFIP guidelines. Homeowners seeking coverage late in storm season often expect immediate protection once payment is made. That expectation persists because urgency feels reasonable when severe weather is approaching. Policy timelines rarely feel intuitive under pressure.
• Waiting periods apply to most new policies
• Limited exceptions exist for specific scenarios
• Last-minute purchases create timing issues
7. Flood Claims Cover Everything
Flood insurance policies include defined limits on both building and contents coverage, particularly under NFIP programs. Finished basements, landscaping, and temporary living expenses often fall outside covered losses. This misunderstanding endures because flood damage feels complete even when coverage is not. Emotional impact clouds policy details.
• Coverage limits vary by policy type
• Basement-related losses face restrictions
• Personal property caps apply

Why These Flood Insurance Misunderstandings Continue
Flood insurance misunderstandings endure because they often sound reasonable until tested by real-world events, and by then correction comes too late. Flood insurance works differently than homeowner’s insurance. Each section above shows how assumptions form, quietly spread, and resurface after every major storm cycle. Industry experience consistently proves that clarity before flooding leads to far better outcomes than explanations after damage occurs. Preparation changes results.
Key Takeaways on Flood Insurance Misunderstandings
• Flood insurance operates separately from homeowners coverage
• Properties outside high-risk zones still experience flooding
• Disaster assistance does not replace insurance protection
• Waiting periods affect when coverage begins
• Policy limits shape claim payouts